Owner-occupied premises
The workshop, the office, the yard, the shop you trade from. The business and the building have to make sense together.
Premises, commercial property, and refinance for New Zealand businesses. From a family company to a nationwide operation.
Commercial property
Commercial lending in New Zealand is how a business buys, refinances, or invests in property. Working capital, a vehicle, or a cash-flow gap, with no property changing hands, is a different conversation.
The workshop, the office, the yard, the shop you trade from. The business and the building have to make sense together.
A property with a tenant. The lease, the tenant, and the building matter as much as your own balance sheet.
A commercial facility coming to the end of its term, or a structure that no longer matches how the business operates.
Some projects are a construction loan, some are a commercial facility. We say which one it is before anyone spends money on the wrong application.
Need stock, plant, or a facility because the bank said no? That is business lending. Building a new home is a construction loan. A residential rental sits with investment property. New to this? Start with how to invest in commercial property.
The assessment
A commercial file is not a home-loan application with a different address. These are the four things that decide whether a lender will read it.
01
What it is, where it is, and what a valuer will actually support. Commercial security is not priced like a house.
02
Your own business, or a tenant on a lease. Lenders read those two files differently.
03
Company, trust, or a mix. This is where your accountant earns their place on the file, before a lender does.
04
Usually more than a home loan, and never a number we invent before seeing the property. We run it against lenders who want this kind of deal.
The network
Entity structure, the agreement, and the valuation are not things we guess at. If you already have those people, we work with them. If you do not, we introduce lawyers, accountants, and valuers from the Orange Network. We are not a substitute for them.
Lenders
Commercial appetite changes by property type and by lender. These are institutions we can take a file to. A name here is access, not a promise they will say yes.
Major banks on the Orange Network panel. Specialist funders are added when the property or the entity needs them.
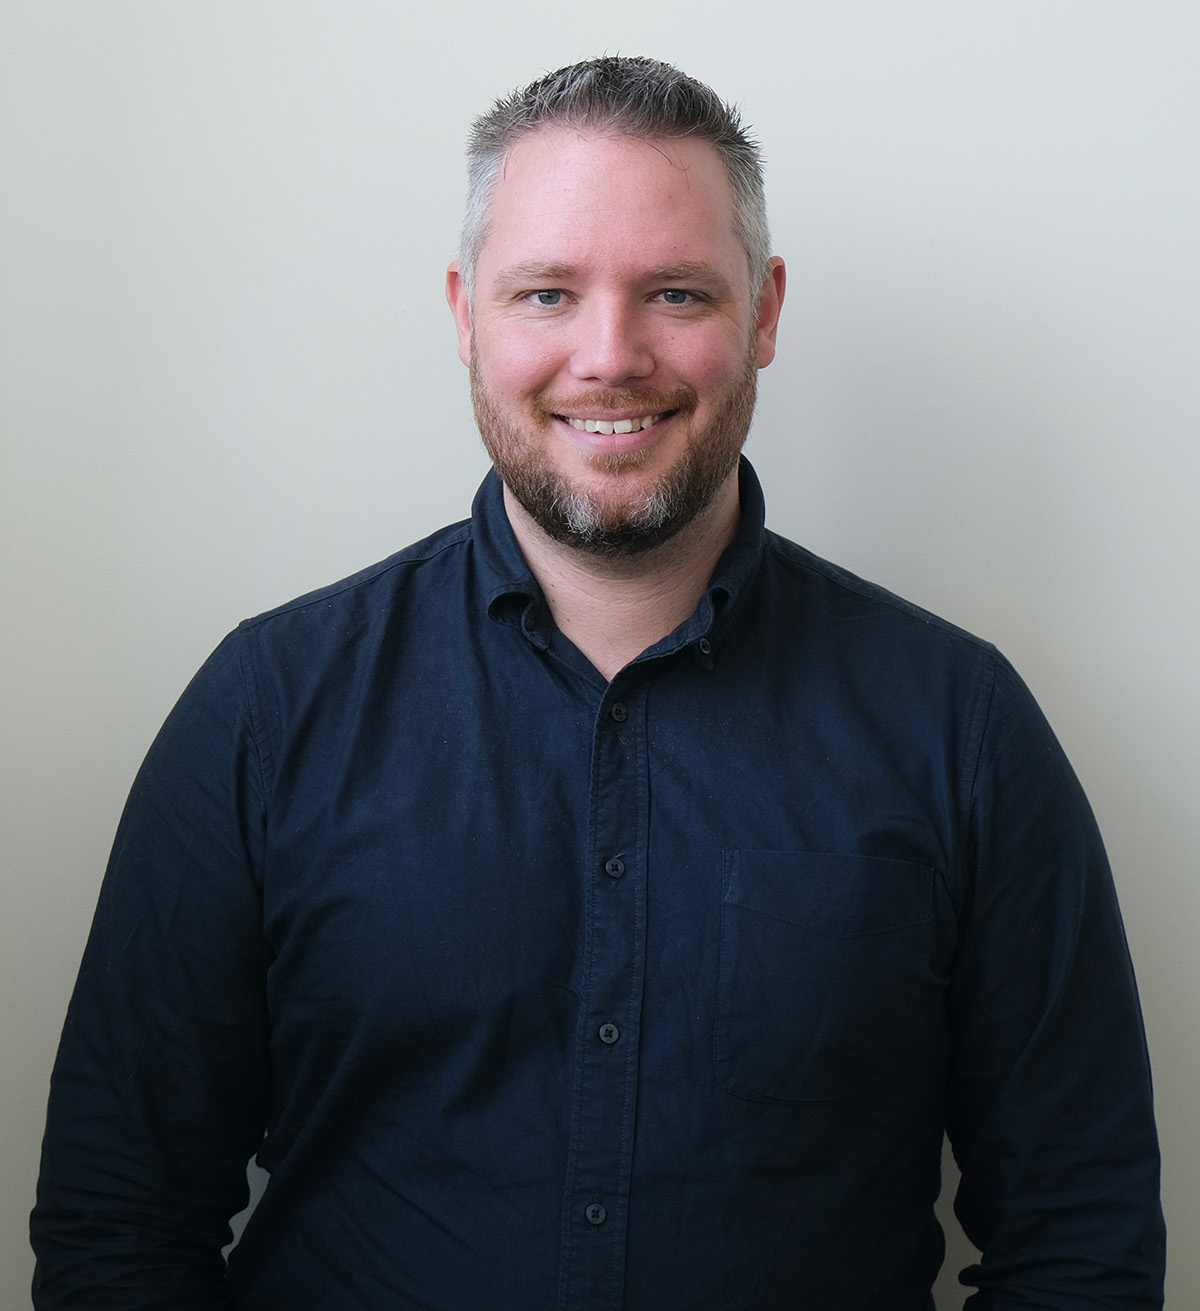
Chad Weber
Head of Lending
Chad is an experienced mortgage broker committed to helping Kapiti residents achieve their financial goals. He specializes in assisting first-home buyers, investors, and those looking to refinance or secure business financing, offering tailored advice to suit each client's unique situation. Outside of work, Chad enjoys traveling, renovation projects, exploring new culinary experiences, and investing, reflecting his passion for creativity and learning.
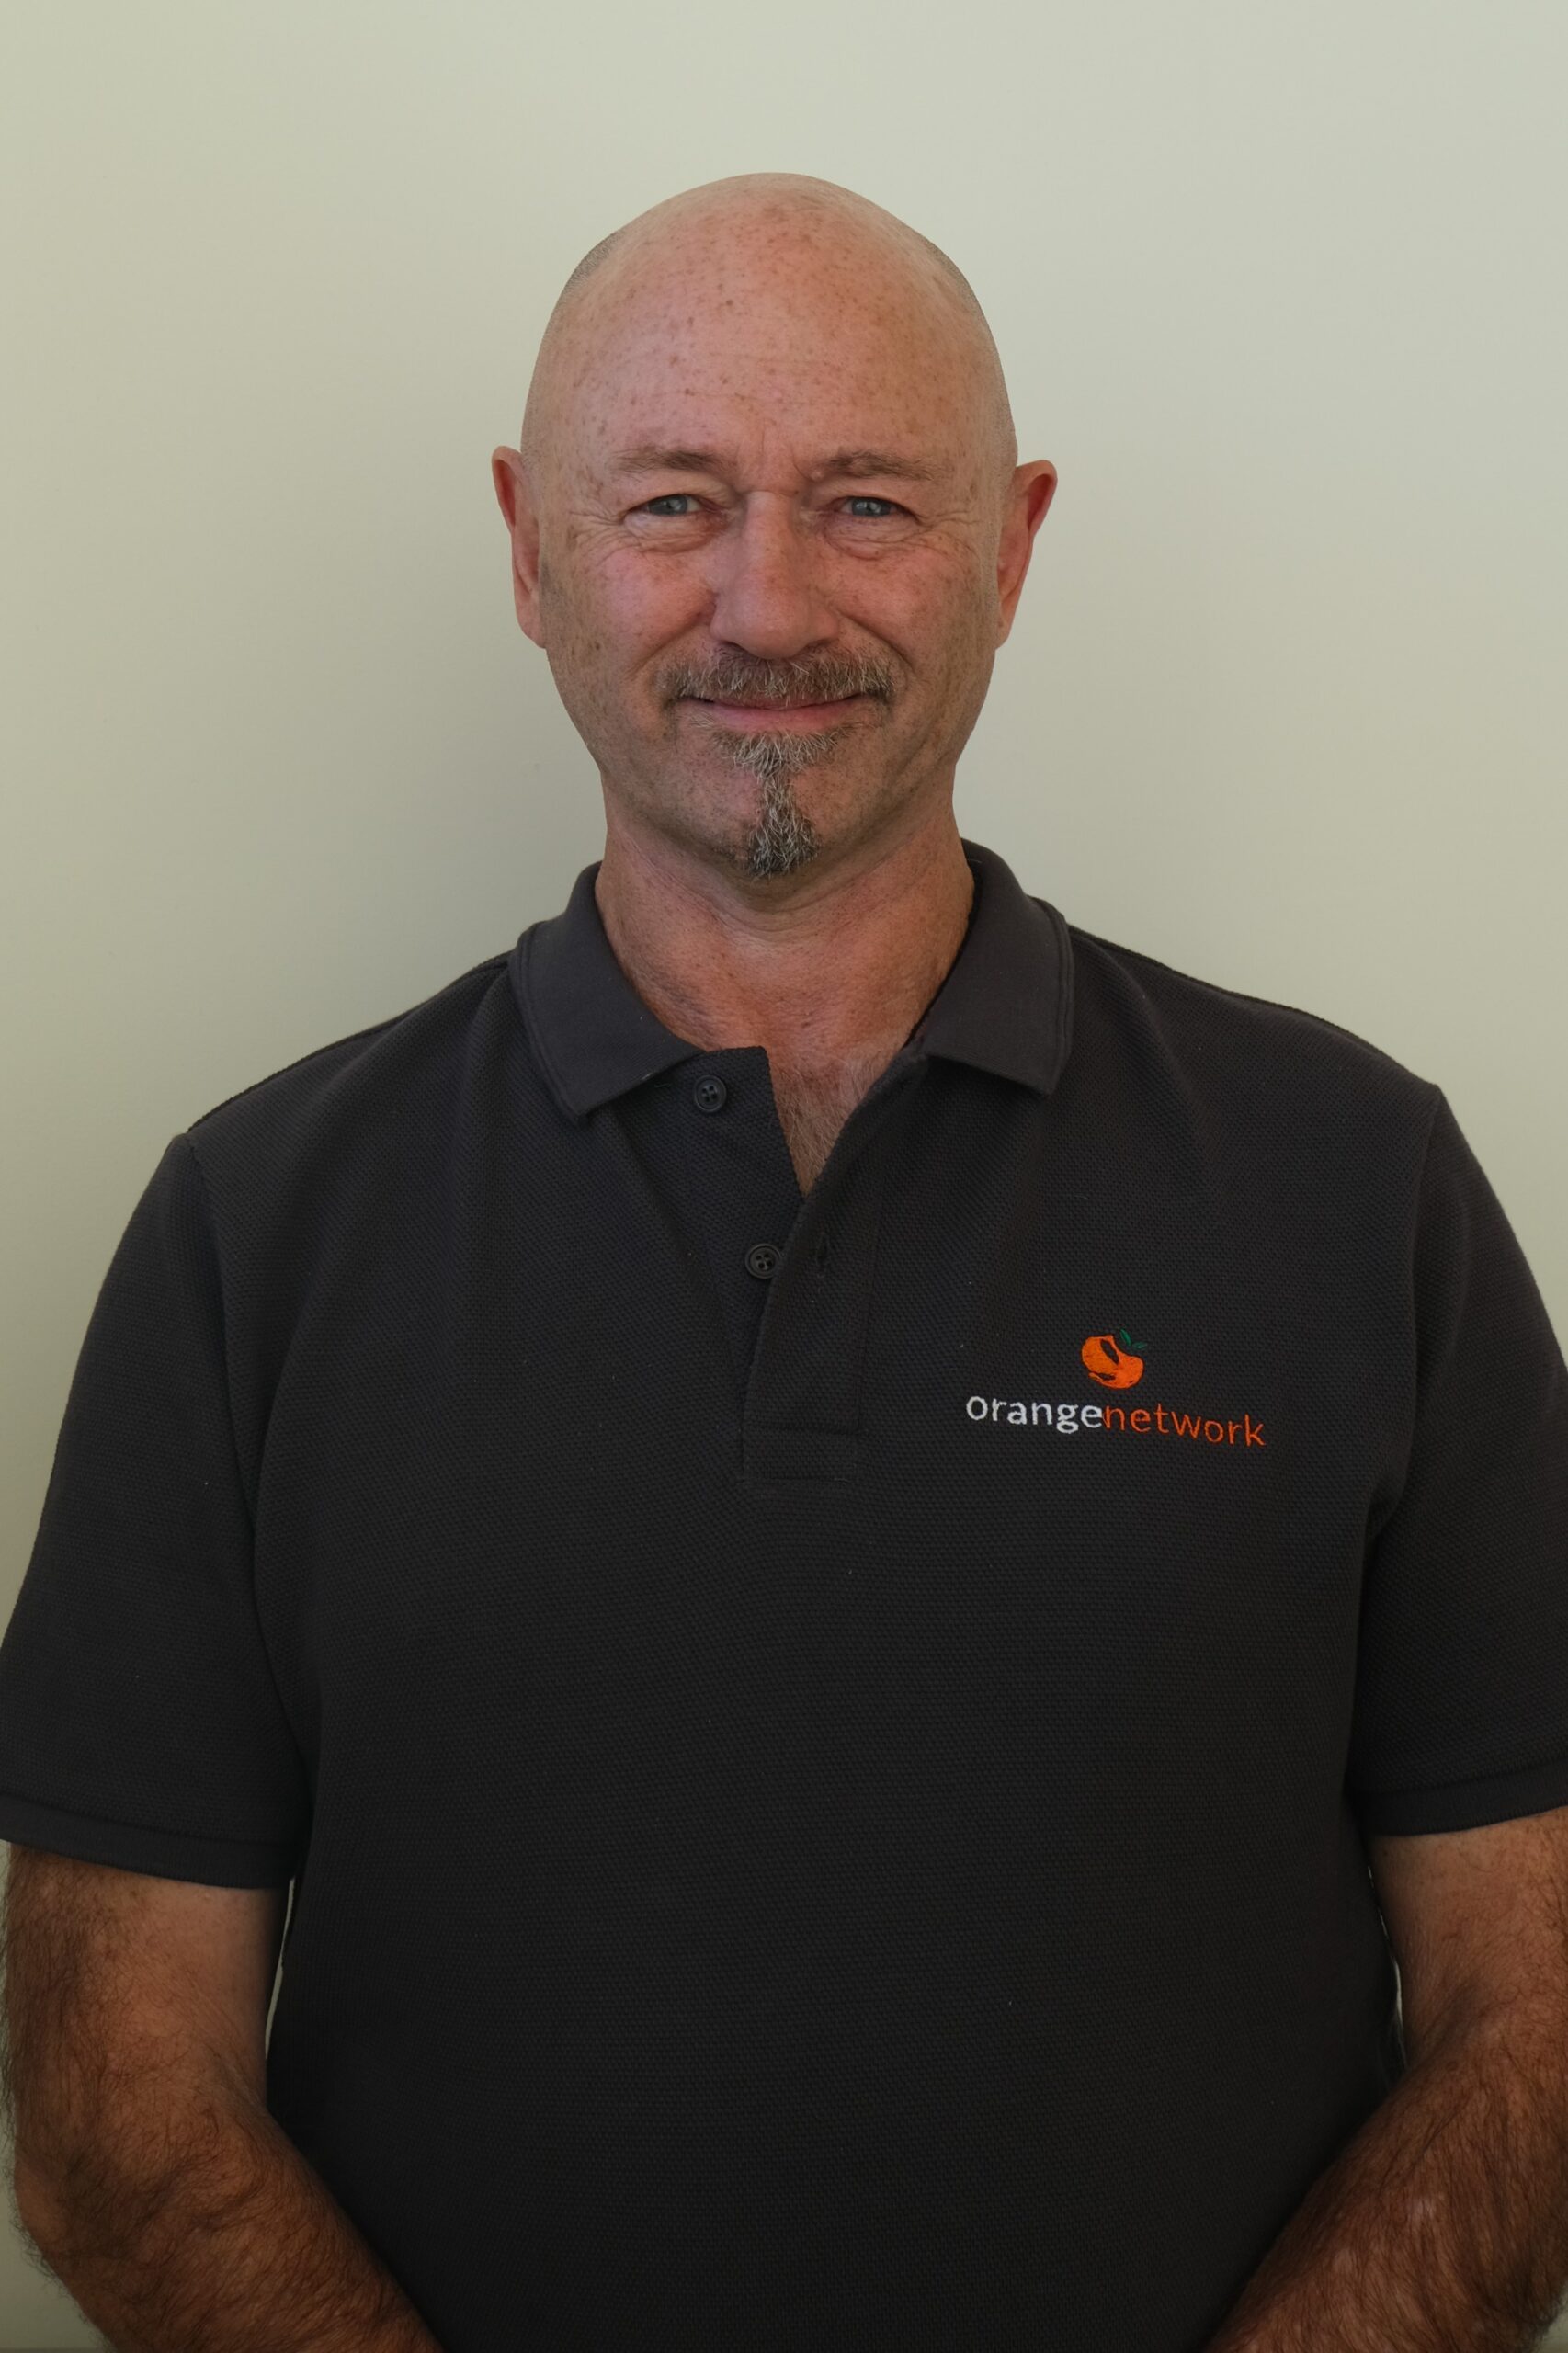
Lindsay Hill
Relationship Manager, Mortgages
Lindsay brings more than 30 years of experience across banking, finance, sales, and customer relationships. He is particularly passionate about working with self-employed business owners and growing SMEs who need a proactive partner to navigate lenders, compare options, and present a strong proposal. Lindsay takes the time to understand each client's goals, then connects them with the wider Orange Network team and lending partners to build flexible, future focused structures across business lending, commercial property, and personal borrowing. Outside of work, Lindsay is usually found on the water fishing from a kayak, out on his motorbike, or spending time with his dog, Mr Arlo Gump Wookie, somewhere close by.
Where
Family-run companies on the Kapiti Coast, Wellington businesses buying their first premises, and operators whose sites are somewhere else in the country. In person from Paraparaumu, or online.
No charge for the first conversation. Address, what you want to do with it, and whether you already have an accountant or lawyer on it.
We will come to you in Wellington or on the Kapiti Coast, or jump on a call. Tell us what suits.